If a project owner just asked you for a performance bond, you probably have questions nobody has answered yet. What is it? Who pays. What happens if somebody files a claim. Whether you’ll even qualify.
This guide covers all of it in plain language. We’ve spent more than 12 years putting these programs together for contractors, and the process is a lot less mysterious once you understand what carriers are actually deciding.
What is a performance bond and its role in construction
Performance bond definition
A performance bond is a three-party guarantee between the principal (the contractor), the obligee (the project owner), and the surety (the carrier). It guarantees the contractor will complete the project according to the contract terms. If the contractor defaults, the surety investigates and either sees the work through or pays the obligee’s losses up to the bond amount.
Why performance bonds exist
Public construction is paid for with tax dollars, so the government requires a guarantee that the money produces a finished project. That’s the whole idea behind the Miller Act, passed in 1935, and the Little Miller Acts that followed in every state.
Private owners aren’t required to ask for bonds, and many don’t. The sophisticated ones do, because the cost of a bond is small next to the cost of a walk-off on a job they’ve financed. You can see the full range of what gets bonded on a construction project in our overview of construction surety bonds.
The three parties in a performance bond
You’re the principal. You’re the one obtaining the bond and the one on the hook for it.
The obligee is whoever requires the bond. On a public job that’s the government agency. On a private job it’s the owner or the developer. If you’re a general contractor requiring bonds from your subs, you’re the obligee on those.
The surety is the carrier standing behind you. Most are divisions inside large insurance companies like Travelers or Zurich, though a handful of carriers write surety only.
Notice that the obligee is always the party upstream of whoever obtains the bond. First-tier subs can require bonds from second-tier subs. Any contractor can require bonds from a supplier. The relationship repeats itself down the chain.
How does a performance bond work
A performance bond is not insurance
This is the piece most people get wrong, and it explains everything else.
A bond looks like an insurance policy. It works differently. Insurance expects losses and prices them into the premium. Your auto carrier knows a percentage of its policyholders will crash, and your rate reflects which category you fall into.
Surety underwriters aim for a zero loss ratio. When a carrier issues your bond, it expects never to pay a claim. It isn’t pricing risk, it’s making a credit decision that you’ll perform. That’s why obtaining a bond feels more like applying for a loan than buying a policy.
Indemnification and the general indemnity agreement
Here’s the part that deserves your full attention before you sign anything.
When you sign a general indemnity agreement with a surety carrier, your corporate and personal assets stand behind the bond. If the carrier pays a claim, it will look to recover those losses from you. That usually includes all owners and their spouses.
There’s no corporate veil. All indemnitors are personally liable for paid claims.
It sounds harsh. It’s also the reason the system works. Indemnification is real skin in the game, and it means a contractor who’s been awarded a bonded project will do everything in their power to finish it. It’s also why carriers are so thorough about who they’ll support in the first place.
When the bond ends
The bond doesn’t expire at substantial completion. It stays in force through the warranty period.
One year of warranty is built into base rates. Additional years carry a small surcharge, and three years is usually the maximum a carrier will go. Worth knowing before you agree to a five-year warranty in a contract.
One more wrinkle: bond close-out means different things to the obligee, the principal, and the carrier. If you need a bond formally released, ask early.
The different types of construction bonds
Four bonds show up on construction projects. Bid bonds, performance bonds, payment bonds, and warranty or maintenance bonds. Collectively the industry calls these contract bonds. Performance and payment bonds get their own sections below, so here are the other two.
Bid bonds
A bid bond guarantees you submitted your bid in good faith and will enter the contract if you win. The limit is usually 5% or 10% of the bid amount, sized to reflect what it would cost the owner to hire the next highest bidder if you walked.
Carriers don’t charge for bid bonds. What they do instead is underwrite you at the bid stage, which means the real work happens before you’ve won anything.
Warranty and maintenance bonds
These cover defects and repairs for a set period after the project is finished. Sometimes they’re written separately.
More often the warranty obligation rides along inside the performance bond, which is why that first year is included in your rate.
Performance and payment bonds: how they work together
Performance and payment bonds are issued together, each equal to the contract value. The performance bond guarantees you’ll complete the project per the contract terms. The payment bond guarantees your subcontractors, suppliers, and laborers get paid.
They’re two separate promises to two different audiences, and they’re almost never sold apart.
What is a payment bond
A payment bond guarantees payment to the lower-tier participants on your project. Subcontractors, suppliers, and labor.
If you don’t pay them, they file against the bond and the carrier makes them whole. Then the carrier comes to you for reimbursement under your indemnity agreement.
Payment bond claims are far more common than performance bond claims. Performance claims are rare but severe. Payment claims are routine, usually smaller, and often the result of a dispute rather than an actual inability to pay.
Performance bond vs payment bond
| Performance bond | Payment bond | |
|---|---|---|
| Who it answers to | The project owner | Subcontractors, suppliers, labor |
| What it guarantees | Completion per the contract | Payment for work and materials |
| Who can file a claim | The obligee | Unpaid lower-tier parties |
| Claim frequency | Rare, severe | More frequent, usually smaller |
| Premium | Charged on this bond | Included, no separate premium |
The practical distinction: if you’re a subcontractor worried about getting paid, the payment bond is the one that matters to you. The performance bond does nothing for you. Contractors mix this up constantly.
Why the payment bond matters more on public work
On private construction, an unpaid sub or supplier can file a lien against the property. The lien stops the property from being sold until the payment dispute is resolved. That’s real leverage.
You can’t lien public property. So on public work the payment bond isn’t just one option among several. It’s the only recourse an unpaid sub or supplier has.
Payment bonds vs mechanics' liens on private work
On private jobs, subs have both routes available, and a bond claim isn’t a prerequisite for a lien or a lawsuit. Multiple remedies can run at the same time.
The timing is where people get hurt. Colorado subcontractors have four months from last furnishing labor or materials to file a mechanics’ lien, less the notice of intent period, then six months after substantial completion to foreclose. A sub whose scope finishes early can watch those rights lapse before retainage is even due.
Bond claim windows are usually longer, but they’re governed by the specific bond form, not by statute. Read the form. Our walkthrough on how to file a payment bond claim covers the notice sequence and the deadlines that actually bind.
How performance bonds protect project owners and contractors
Protection for project owners
For the owner, the bond turns an unfinished building into a recoverable loss. If you default, they have a solvent carrier obligated to either finish the job or write a check.
There’s a second benefit owners undervalue. Before the bond was ever issued, a carrier reviewed your financials, your work history, and your capacity, and concluded you could do the work. The owner got a free credit check on their contractor.
What contractors get out of being bonded
Contractors ask a fair question. Why would I want a bond that gives me no direct benefit and costs me money?
Because not every contractor can get one. The larger the bond you can obtain, the less competition you face on the work you want.
Prequalification is the other half. Especially in private construction, project owners and general contractors would rather work with companies that have been prequalified by a surety. Being bondable is a great marketing tool, and a bondability letter costs you nothing to request.
The process of obtaining a performance bond
How to get a performance bond
Start with an agent who does surety work specifically, not an insurance generalist who writes a bond occasionally. Ask what carriers they’re appointed with.
From there the agent gathers your underwriting package and builds a submission. The carrier reviews it, comes back with a program, and you decide whether the terms work. Once you accept, bonds get issued per project against the limits you’ve been approved for.
The part contractors don’t expect is how much of the outcome depends on them. You dictate the quality of your program. Are you producing the information carriers ask for? Are you willing to keep money in the company instead of pulling it out? Those choices matter more than an agent’s negotiating skill. Our new to bonding page walks through what that first submission looks like.
How long it takes
On an established program, most bond requests are approved within a couple of hours and executed for next-day delivery.
Starting from scratch is different, and the timeline sits almost entirely with you. With clean financial statements it moves fast. Without them it takes as long as it takes to produce them.
Performance bond requirements for contractors
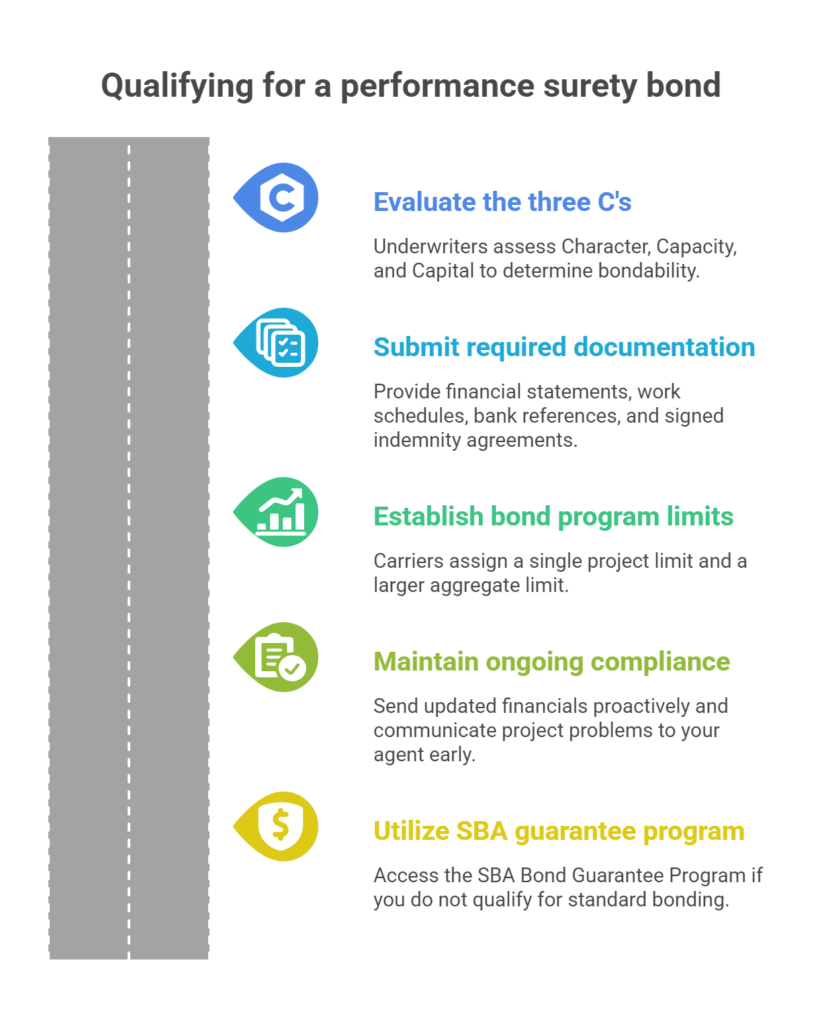
Qualifying for a performance surety bond
There’s no single hurdle you clear. Carriers are building a picture of whether you’ll finish what you start, and the answer comes back as a program with limits rather than a yes or a no.
New companies and contractors with imperfect records get bonded all the time. If you can show you’ll complete the project and honor the terms, it’s possible. The challenge is producing that information clearly. Our guide to the surety bond approval process covers what happens after your file lands on an underwriter’s desk.
The three C's of underwriting
Underwriters summarize a long list of criteria into three C’s. Character, Capacity, and Capital.
Character is the most important, and it surprises people. If a contractor is unwilling to do whatever it takes to complete a project, they aren’t bondable. The proxy carriers use is credit, on the theory that someone who dodges creditors represents a character risk. A personal score above 675 opens access to bonds up to $400,000. Excellent credit combined with strong references can reach $750,000. So a young company with a disciplined owner can qualify for meaningful limits.
Corporate credit gets overlooked. Carriers pull Dun & Bradstreet and Experian to see whether you pay your suppliers on time. Slow pay shows up there, and it costs you.
Capacity is your ability to actually build the thing. Largest job completed to date, similar project experience, backlog both bonded and unbonded, equipment, and the resumes of your key people. If your biggest completed job is $1 million and you ask for a $10 million bond, the answer is no. The plan is to stairstep, taking work no larger than roughly twice your largest completed project and letting your limits grow behind your record.
Capital is cash, working capital, equity, personal net worth, and access to a bank line of credit. Working capital is current assets minus current liabilities. Some underwriters weight equity and net worth more heavily, others focus on working capital.
Your program will carry two numbers. A single limit for any one project, and a larger aggregate limit for everything you have open at once.
Documentation and compliance for performance bonds
Expect to provide business and personal financial statements, a work in progress schedule, your largest completed jobs, a bank reference, a signed indemnity agreement, and authorization to pull credit.
Two things keep a program healthy after it’s in place. Send updated financials without being chased, and tell your agent about problems early. An underwriter who learns about a bad job from you keeps supporting you. One who learns about it from a claim notice does not.
Compliance matters on the project side too. Licensing, contract terms, and the notice requirements in your bond form are all conditions you agreed to.
If you don't qualify yet
The SBA Bond Guarantee Program has been around more than 50 years and stays underutilized. The SBA acts as a backstop to the carrier. If the carrier takes a loss on an SBA-backed bond, the SBA reimburses it, which widens the appetite of every participating carrier. It’s built for firms in business under three years, with limited job size history, thin financial resources, recent losses, or credit issues.
The most useful piece is how the SBA handles a bank line of credit. It treats an available line as a current asset and allows twenty times the available balance when calculating your aggregate limit. A contractor with negative working capital and $100,000 available on a line of credit can reach up to $2 million in bonding, assuming the financial statements support it.
Which brings up the best advice in this article. Access to bonding works like access to capital. Get it before you need it. Open the line of credit, don’t draw on it, and let it work for you at renewal. Our guide to the SBA Surety Bond Guarantee Program has the full picture, including the paperwork, which has gotten much lighter.
Cost implications and who pays for a performance bond
How much a performance bond costs
Performance bond rates generally run 0.5% to 3.5% of the contract price. Where you land depends on your credit, your financial statements, the project type, and the duration.
The payment bond premium is included. So is the bid bond. On a $1 million contract you’re looking at roughly $5,000 to $35,000 for the pair.
Rate matters more than contractors think. Just like any raw material, a higher cost makes your bid less competitive against a contractor with a better program. We’re appointed with 15 surety carriers and we market accounts to the underwriters most likely to compete for them. For a full breakdown of what moves your number, see our guide to construction surety bond costs.
Who pays for a performance bond
You do. The contractor obtaining the bond pays the premium.
In practice you build it into your bid, so it becomes part of the contract price the owner pays. It’s a line item in your estimate, not an out-of-pocket expense.
Worth noting what you’re buying. The premium buys the owner a guarantee. It doesn’t buy you protection, because if the carrier pays out, you owe that money back under your indemnity agreement. What you’re really buying is access to work you couldn’t otherwise bid.
Understanding the claims process in performance bonds
Say the owner claims you aren’t completing the project and files on the performance bond. This is where suretyship gets genuinely unusual.
The carrier has responsibilities to both the obligee and the principal. It won’t automatically agree with the obligee and pay, and it won’t automatically protect you either. The carrier will remain neutral, investigate the claim, and if the claim is appropriate, proceed to resolve it. Conversely, it can deny the claim and defend you as needed.
No other financial instrument works this way. A bank honoring a letter of credit pays on demand without asking whether the draw was justified.
Filing a performance bond claim
For an obligee, the sequence usually runs like this. Document the failure. Give the contractor written notice and an opportunity to cure. Declare default and terminate the contract if the failure continues. Notify the surety in writing and state what you’re asking for.
Then the carrier investigates. It reviews the contract and the bond, visits the site, pulls the payment history, and interviews the people involved. It’s looking at whether a genuine default occurred and whether the obligee followed the steps the bond requires.
Those steps matter enormously. Most bond forms treat notice and a formal declaration of default as conditions the obligee has to satisfy before the surety owes anything.
How the surety resolves a valid claim
Carriers have four ways to resolve a claim they’ve accepted. They can take over the work and complete it. They can supplement your operation with money or resources so you finish it yourself. They can replace you with another contractor. Or they can pay the obligee’s damages up to the bond amount.
Which route they take depends on how far along the job is, what a replacement would cost, and how cooperative you are. Contractors who stay in the room during an investigation get supplemented. Contractors who go quiet get replaced.
Then the carrier looks to recover what it paid, through the indemnity agreement.
Dispute resolution and performance bond claims
When the obligee and the surety disagree about whether a claim is valid, it moves through mediation, then arbitration, then litigation, depending on what the contract and bond specify.
If the carrier concludes the claim is improper, it defends you through those same channels with its own counsel. That’s the dual obligation working in your favor, and it’s the single most underrated feature of a surety bond.
Whichever direction it goes, get a construction attorney involved early. That advice holds for every party on the project.
How performance bonds work in the public vs private sector
Public projects
On public work, bonds are required by statute and the thresholds are set for you.
| Level | Threshold |
|---|---|
| Federal, Miller Act | Over $150,000 |
| Colorado, state projects | Over $150,000 |
| Colorado, cities and counties | Over $50,000 |
The Miller Act requires both bonds on federal contracts over $150,000. Every state and most municipalities have similar requirements through Little Miller Acts. Check your specific jurisdiction, because the numbers vary and some agencies bond below their statutory floor as a matter of policy.
There’s usually nothing to negotiate here. The agency’s bond form is the bond form.
Private projects
On private work, bonds are optional risk management tools. Because of the cost they’re less common, but they clearly add value when used correctly.
Two differences matter. First, the terms are negotiable, and the bond form is often the owner’s or the general contractor’s own, which means the language deserves a careful read. Second, bondability becomes a marketing advantage rather than a checkbox, because a private owner choosing between bidders reads a bondability letter as a credit reference.
Subcontract bonds are their own category. Subcontract agreements carry flow-down clauses from the prime contract, so obligations you never negotiated can land in your scope. Ask specifically how retainage is handled before you sign.
Legal implications and performance bond regulations
Bond forms and why the language matters
The bond form controls, not the general concept of a performance bond.
Default and termination language is the part to focus on. What counts as a default, how much notice you get, what cure period you have, and what the obligee must do before the surety’s obligation is triggered. On public work you’re taking the agency’s form as written. On private work there’s room to push back, and it’s worth using.
Timing provisions are equally important on the payment bond side, since notice and suit deadlines vary by form and by jurisdiction.
State and local variation
Federal law sets the framework on federal jobs. State Little Miller Acts govern state and local work, and every state wrote its own, so thresholds, notice periods, and claim procedures differ.
The practical rule: don’t assume the process you followed in one state applies in the next. Read the statute and the bond, and have a construction attorney review anything unfamiliar before you sign.
Ready to get bonded
If you need a performance bond for a specific project, or you want to raise the limits on a program you already have, call Eddie Maxfield at 720-492-9258 or send us your project details. We’ll tell you what carriers need and what your realistic limits look like.
If you can complete the project, we can tell your story.
Frequently asked questions
What is a performance bond?
A performance bond is a three-party guarantee that a contractor will complete a project according to the contract terms. It’s a credit instrument rather than an insurance policy, and the contractor reimburses the carrier for anything it pays out.
How does a performance bond work?
The obligee declares a default, follows the notice steps in the bond form, and notifies the surety. The carrier investigates neutrally, then either takes over the work, supplements the contractor, replaces them, or pays damages, or denies the claim and defends the contractor.
Who pays for a performance bond?
The contractor pays the premium and builds it into the bid, so the cost ends up in the contract price. Rates generally run 0.5% to 3.5% of the contract price, with the payment bond included.
What's the difference between a performance bond and a payment bond?
The performance bond answers to the project owner and guarantees completion. The payment bond answers to subcontractors, suppliers, and labor and guarantees they get paid. They’re issued together, each equal to the contract value.
Can I get a performance bond with bad credit?
Often yes, at lower limits or through the SBA Bond Guarantee Program. Credit is a proxy for character rather than a pass-fail test, and strong references, a clean work history, and a bank line of credit all offset a mediocre score.
Does a performance bond protect the contractor?
No, and this is the most common misunderstanding in surety. The bond protects the obligee, and the contractor indemnifies the carrier for any loss, which is why a bond is a business development tool rather than a safety net.
Published April 6, 2024. Updated August 2026.
About Tom Patton
Tom Patton is the President of Evergreen Surety and a Certified Construction Industry Financial Professional (CCIFP), leading surety bond programs for contractors, developers, and energy producers across the United States and Canada. Drawing on 15+ years of specialty surety experience and appointments with 15+ carriers, Tom is known for building programs that perform when called upon and solving the bond problems other agents walk away from.