Most contractors want one number before they read anything else, so here it is. Performance and payment bond rates typically run 0.5% to 3% of the bond limit. On a $1,000,000 bond package, that’s a premium between $5,000 and $30,000.
You’re paying a percentage, not the face value of the bond. That distinction stops more contractors from bidding bonded work than any other misunderstanding in this business.
The rest of this guide explains what puts you at the low end of that range instead of the high end, who actually pays the premium, and what you can do this year to bring your rate down. We’re a surety-only agency, so this is the conversation we have every day.
Need a number for a specific bond? Request a bond quote or call 303-520-0249 and we’ll give you a real figure, not a range.
Key Takeaways
- Rates for performance and payment bonds typically range from 0.5% to 3% of the bond limit. A $1,000,000 P&P package usually costs between $5,000 and $30,000.
- Performance and payment bonds are two separate bonds, but carriers issue them together as one product priced at a single combined rate.
- Bid bonds are issued complimentary, so there’s no premium to price into your bid.
- The cost is typically built into the contract, so the contractor doesn’t directly incur the expense.
- Understanding the parties involved in surety bonds, such as the principal, surety, and obligee, is crucial.
- Underwriters price bonds off the three C’s: character, capacity, and capital. Character, measured largely through credit, is the most important.
- Indemnity is a real cost beyond the premium, and it can be reduced over time.
- Managing surety bond costs involves improving financial practices, and better financial reporting is the clearest lever you have.
The Fundamental Role of Construction Surety Bonds
Construction surety bonds are key in the building sector. They protect both project owners and contractors. These bonds ensure that contractors will do their jobs and finish projects as promised.
That dual purpose explains the pricing. You’re not insuring yourself against your own failure. You’re buying a carrier’s endorsement of your ability to perform, and that endorsement gets underwritten like credit.
Essential Protection for Project Owners
Construction surety bonds shield project owners. When starting a construction project, owners put in a lot of time, money, and effort. But, there are risks, such as a contractor not finishing the job.
Surety bonds reduce these risks. If a contractor defaults, the surety steps in to see the work completed, and the bond covers the owner’s loss up to the bond limit. This allows the project to be completed without major financial losses.
Contractors' Assurance to Fulfill Contractual Duties
For contractors, surety bonds prove they can meet their contractual promises. Getting a bond means passing a thorough check by a surety company. This review looks at their finances, past work, and trustworthiness.
With a surety bond, contractors show they are committed to their work. This builds trust with project owners. For most contractors, it’s also the door into larger construction surety bonds and the bigger projects that come with them.
Examining the Parties Involved in Surety Bonds
To really grasp how surety bonds work, it’s important to know about the three main groups involved. These are the principal, surety, and obligee. They each have unique roles in the bond’s terms.
Identifying the Principal, Surety, and Obligee
The principal is usually a contractor who qualifies for and obtains the bond. They promise to do the job outlined in the bond. The principal then starts the project, showing they can finish the work.
The surety is often an insurance company. They promise the obligee that the principal will do their job. Before supporting the bond, the surety checks if the principal can deliver. This way, the surety can complete the project if the principal can’t.
The obligee is the party who requires the bond from the principal. Often, this is the project’s owner, like a government agency or a private company. The obligee can also be a general contractor that requires bonds from a subcontractor. The obligee uses the bond as security. If the principal fails, the obligee can claim money from the bond.
The Indemnity Agreement: Contractors' Financial Obligation
The principal must sign an indemnity agreement. This shows they agree to cover any bond claims. It’s their financial promise to the surety.
This agreement formalizes the relationship between the principal and surety. It is a strict legal document that allows the surety to recover any losses it incurs on behalf of the principal. A general indemnity agreement needs to be signed by all owners with more than 10% equity, as well as their spouses. This commitment to indemnify the surety is a key component of the bonding process.
Indemnity belongs in any honest conversation about bond cost, because it’s a real obligation even though it never shows up as a premium. All owners and their spouses can be personally liable for claims the carrier pays.
The good news is that it’s not permanent. Larger companies with strong corporate balance sheets can reduce or remove personal indemnity, including a spouse’s signature or a primary residence. Getting there takes benchmarking and clear financial thresholds that answer underwriter objections before they’re raised. That’s work we do with clients as part of building a program, not a favor we do at renewal.
Types of Construction Bonds and Their Specific Functions
In construction projects, many bonds are key to a project’s success. Each bond has its own role. These bonds protect different people involved in the project. Surety bonds for construction projects fall into three main types, and they don’t all carry a premium.
Let’s look at the key construction bonds and what they do.
Performance bonds guarantee the contractor completes the project according to the contract terms. Payment bonds guarantee that subcontractors and suppliers get paid for their work. Bid bonds guarantee that a contractor will enter into the contract, and provide the corresponding performance and payment bonds, if awarded the project.
One project can carry all three at once, since each protects a different party. If you’re new to surety bonds, that overlap is usually the first thing that needs untangling.
Risk Assessment: How Surety Companies Evaluate Contractors
Surety companies have a detailed method to check if contractors are fit for surety bonds. This includes looking at how well the contractor can stick to their contract. They pay special attention to financial health and how well past projects were managed.
The Importance of Contractors' Financial Health in Surety Bonding
The financial health of contractors is key in the surety bond process. Surety companies look at whether contractors have enough money to finish the project. They consider liquidity, working capital, debt ratios, and financial strength.
Working capital is your current assets minus your current liabilities, and it’s the number most underwriters start with. Some weight equity and personal net worth more heavily instead. If you already have a program, ask your underwriter which metric they care about most, because the answer tells you where to put your effort.
What every underwriter wants to see is the same. Large cash balances and an untapped bank line of credit.
Past Project Performance as a Determinant in Bonding
Contractors’ previous work success is also crucial. Surety companies review their history to see if they can deliver on time and within budget.
This review includes looking at the contractor’s experience, skill level, and quality commitment. They watch out for delays, overspending, and legal issues. Contractors with a strong project history are more likely to be favored in the bonding process.
Capacity follows directly from that history. If your track record is $1,000,000 projects and you ask for a $100,000,000 bond, the underwriter says no. The approach that works is to stairstep up, taking on projects no larger than roughly twice the size of your largest completed job. Done consistently, that’s how a small program becomes a large one.
Surety Bond Cost Breakdown: Factors Affecting Pricing
Getting a construction surety bond involves understanding its costs. The cost of construction bonds is set by three underwriting factors, and knowing them lets contractors plan and budget with real numbers.
The three C’s of underwriting dictate the terms and conditions of a surety bond program.
- Character: largely measured through personal and corporate credit scores.
- Capacity: evaluated based on the contractor’s track record of completing projects of similar size.
- Capital: assessed through factors such as working capital, cash balances, and bank lines of credit.
Of the three, character is ultimately the most important. Credit is the fastest thing an underwriter can verify and the hardest thing to talk your way around, which is why it drives so much of your rate.
The useful part is that all three are things you can work on. None of them are fixed.
Average Construction Bond Rates: What Contractors Can Expect
Bond rates typically range from 0.5% to 3% of the bond limit. For instance, a $1 million performance and payment bond package may have a premium between $5,000 and $30,000.
That’s a six-fold spread on the same bond amount. Bonding rates for contractors vary more by company than by job, which is why two firms bidding the same project can be quoted very differently.
Bond Type | Typical Rate |
Performance and payment bonds, priced together | 0.5% to 3% of the bond limit |
$1,000,000 P&P package | $5,000 to $30,000 |
Bid bonds | Complimentary |
As Tom puts it, just like any raw material, differences in cost can make contractors less competitive with their bids.
Who Pays for a Construction Bond?
You obtain the bond and you pay the premium, but the cost is typically built into the contract. That means it gets funded upstream by the project owner rather than coming out of your margin. You price it into the bid as a job cost, the same way you price material or equipment.
Which leads somewhere counterintuitive. Some contractors want the lowest rate possible so they can bid as aggressively as they can on hard-bid work. Others would rather have a higher rate, because it discourages owners from requiring bonds of them at all. Both are real strategies. Which one fits depends on how you go to market, and it’s worth deciding on purpose. If you run work as a general contractor, surety bonds for general contractors covers how this plays out at the GC level.
Bid Bond Cost
Bid bonds are issued complimentary. There’s no premium, which surprises contractors who assume every bond carries a cost.
The catch is that the bid bond isn’t free of underwriting. The carrier is effectively pre-approving the performance and payment bonds when it issues the bid bond, so the file work happens up front and can take 24 to 72 hours. Don’t call your agent the afternoon the bid is due. Budget time, not money.
Understanding Cost Variations Across Different Bond Types
The cost of surety bonds varies with the bond type. Each bond serves a unique purpose and has different risks.
What varies just as much is the carrier. Every underwriter has a different appetite, and the same account can price differently depending on which market it lands in.
Calculating Rates Based on Project Value
Project value also affects surety bond rates. Surety companies consider project size and complexity. Larger bonds generally price at lower percentage rates than small ones, but the tiering behind that is case-specific. There’s no published schedule you can price yourself against, because where the breakpoints fall depends on your account and the carrier writing it.
What doesn’t change with project size is the underwriting standard. A larger bond gets more scrutiny and a heavier documentation requirement, not a different test.
When Credit Alone Is Enough, and When the SBA Helps
Not every bond needs a full financial review. On smaller limits, carriers will approve on personal credit alone. A FICO score above 675 can provide access to bonds up to $400,000. Excellent credit combined with references can extend that to $750,000.
If your working capital is thin or your company is newer, the SBA Surety Bond Guarantee Program changes the math. The program allows aggregate limits up to 20 times a contractor’s working capital, and it counts the available balance on a bank line of credit toward that calculation. A $100,000 line of credit can support up to $2,000,000 in capacity.
We’re one of the leading SBA-appointed agencies in the country, and the program is routinely overlooked by generalist agents. If you’ve been told your capital won’t support the bond you need, that’s worth a second opinion.
Strategies for Managing Surety Bond Costs
Managing surety bond costs effectively is key for contractors. They can do this by using smart strategies. This includes getting better at handling their finances.
Insights from Surety Bonding Experts
Tom describes the terms and conditions of a surety program as a three-legged stool, consisting of rate, capacity, and indemnity. The ideal program has a strong rate, enough capacity to cover everything you’re chasing, and little to no personal indemnity. Most contractors don’t get all three at once, so they trade.
Some contractors will pay a higher rate in exchange for reduced indemnity. Others will add indemnitors in order to obtain the capacity they need. My clients often dictate the terms and conditions they want. If their current carrier is unable or unwilling to offer these terms, we create competition between carriers.
Tom Patton, President, Evergreen Surety
That last point is the one contractors underuse. An uncompetitive rate is not a fact of life. It’s a signal that your account hasn’t been marketed widely enough. We market accounts aggressively across a wide range of carriers, because that competition is what produces the rate you deserve.
Getting passed to a processor is the other thing that quietly costs contractors money. You get one point of contact here. Not just to obtain bonds, but to work through the issues that come up as the business grows.
Improving Financial Practices to Lower Bonding Expenses
To cut surety bond costs, improving your financial habits is vital.
Pay down debt and build cash. Manage cash flow so you’re funding project costs on time. Keep personal and corporate credit clean. Build a real budget and forecast. Take on work that stairsteps your capacity instead of jumping it. And have a CPA prepare your statements once you’re pursuing larger bonds.
One that gets overlooked is the work in progress schedule. A WIP schedule identifies overbillings and underbillings using percentage-of-completion accounting, and Tom calls it the gold standard of construction accounting. It’s the primary tool underwriters use to evaluate larger programs. Most contractors don’t produce one until an underwriter asks for it.
If you’re chasing your first bonded job, secure your first surety bond walks through what to have ready before you apply.
Not sure which of these is actually holding your program back? We’ll analyze your statements and benchmark your KPIs against the metrics underwriters use.
Public vs. Private Projects: Surety Bond Requirements Compared
Surety bonds are essential in construction, for both public and private projects. They protect everyone involved. The requirements for bonds can differ based on the project type.
Government Projects and the Miller Acts
Public projects, usually backed by the government, follow the Miller Act. These laws demand contractors get surety bonds for large projects. Payment and performance bonds are a must to protect the project owner under these acts.
- Federal public projects over $150,000 require performance and payment bonds per the Miller Act.
- In Colorado, local public projects over $50,000 require bonds.
- Bond requirements on private projects are less universal and are often determined by the project owner based on their risk tolerance.
State-level Little Miller Acts apply similar requirements to state and local work, with thresholds that vary by state. If the project qualifies, the bond is a condition of award, not a negotiation.
Bond Requirements for Residential and Commercial Contracts
Private projects, like commercial developments, might have other bond needs. Surety bonds aren’t legally required for these, but they might still be asked for by project owners. This is to ensure financial safety and lessen risks.
Those requirements are set by the owner or developer, and they vary with project size, complexity, and how well the owner knows you. Some private owners bond everything. Others bond nothing until a project crosses an internal dollar threshold.
Public Projects (Miller Acts) | Private Projects |
Mandatory payment and performance bonds | Bond requirements set by project owners or developers |
Specific threshold for bond requirements | Varies based on project size and scope |
Government-funded projects | Non-government funded projects |
The Application Process for Construction Surety Bonds
Understanding the application process for construction surety bonds is essential if you’re a contractor.
Understand what the specific project requires first, since a small bond and a $10,000,000 P&P package are different exercises. Then get the file complete before you submit it, because gaps are the most common cause of delay. The full document checklist is further down this page.
Then communicate, because that’s usually what decides a tough account.
“Virtually every great win we’ve had has come down to our ability to communicate better between the underwriter and the principal. Other agents often give up too quickly or can’t communicate effectively enough to determine what actually needs to be presented to obtain approval. We figure out what the underwriter actually needs and make sure the client can provide it.”
Tom Patton, President, Evergreen Surety
Role of Surety Bond Agents: Connecting Contractors with Sureties
Contractors often need surety bond agents to find good sureties. These agents are key in making the bonding process smooth. They ensure contractors get the best bonding agencies for their needs.
Evaluating Reputable Surety Bonding Agencies
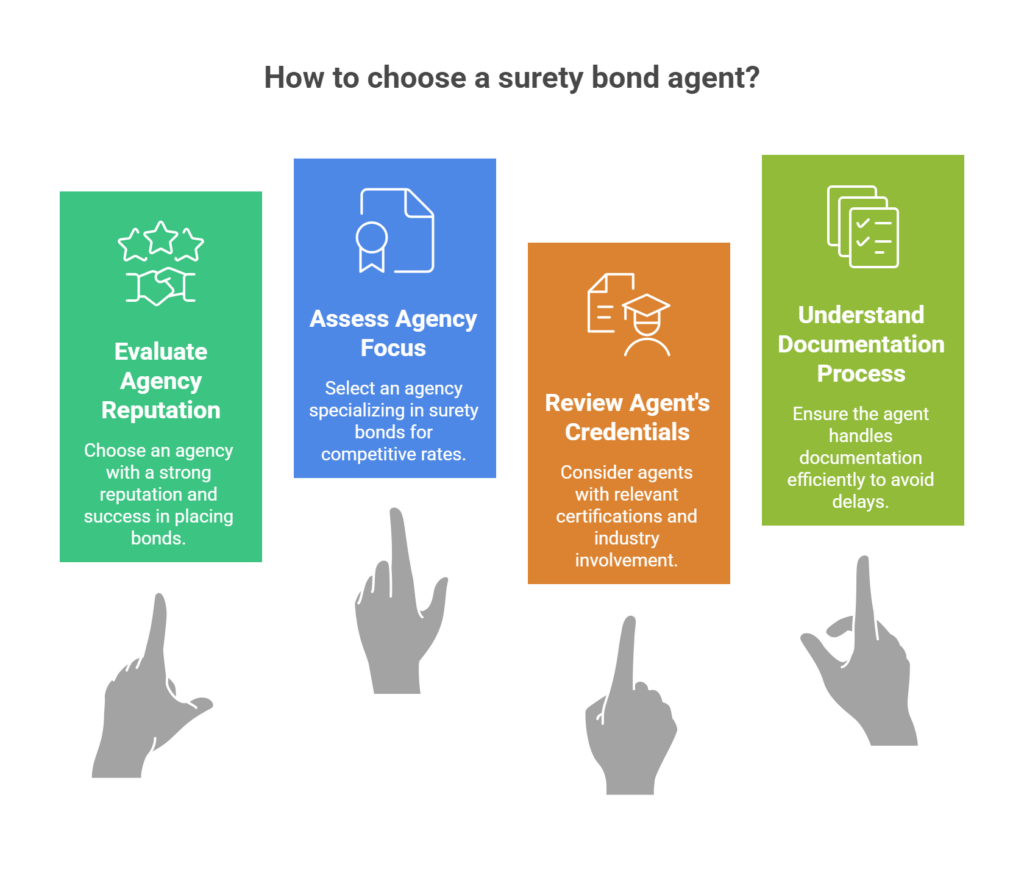
Choosing the right bonding agency is crucial for contractors. They should look into the agency’s reputation and success in placing bonds. Good agencies understand the industry well.
The first question to ask is whether surety is the agency’s focus or a side line next to auto and general liability. We only issue surety bonds, which means we know which carriers are most competitive for a given risk profile and can argue for a better rate with something behind it.
Tom founded the agency after more than a decade in independent surety agency work. He’s President of the Rocky Mountain Surety Association [verify: confirm current title before publication], holds the Certified Construction Industry Financial Professional (CCIFP) designation, has been an AGC of Colorado member since 2014 and a CFMA member for ten years, and presents bond education for Denver International Airport and the Colorado Department of Transportation. He works through a 50-point checklist with clients to find the specific areas where a program can be improved.
Providing Necessary Documentation for Bond Approval
Surety bond brokers help contractors with the paperwork for bond approval. Brokers make sure all documents are right and submitted on time. This makes getting a bond easier.
A good agent assembles that package rather than handing you a checklist. Getting it right the first time matters more than getting it in fast, because an incomplete file that gets declined is harder to fix than one that took an extra day.
A Closer Look at the Cost of Construction Performance Bonds
Contractual Factors Influencing Bond Rates
The cost of construction performance bonds is shaped by different factors. Performance bond cost isn’t quoted on its own, since the payment bond is issued alongside it under a single combined rate. Your rate follows your credit profile and the program terms your carrier will offer. Project characteristics matter to the extent they affect whether the carrier believes you can perform.
Contract terms are part of this, and they’re worth reviewing before you sign. Clauses that expose you to outsized liability can affect both your capacity and your rate. Our guide to performance bond requirements covers what the bond actually obligates you to.
How Rates Decline for Larger Contracts
Larger contracts often carry lower bond rates, and the reason is the rate structure itself.
Bond rates get written one of two ways. A flat rate applies a single percentage against the full contract value, so a 2% rate on a $2,000,000 contract produces a $40,000 premium.
A sliding scale works differently. It breaks the contract value into tranches and applies a lower percentage to each successive one, so only the first slice gets priced at the top rate. Same contract, meaningfully lower premium.
Here’s the part that matters for your program. Contractors typically start on a flat rate under a fast bond program, and as they move into a standard surety program the carrier usually shifts them to a sliding scale. That shift is what makes premiums drop as contract values climb. The tranche breakpoints vary by carrier and contract type, so there’s no universal schedule to plan against.
Capacity works alongside rate. Capacity is measured in single and aggregate limits, so a contractor might have a $1,000,000 / $3,000,000 program, meaning single bonds up to $1,000,000 and total outstanding bonded liability up to $3,000,000.
Liability is measured on a cost to complete basis, so as you run off bonded work your outstanding liability drops and frees up aggregate capacity. Some underwriters measure cost to complete against your total backlog, while others look only at bonded projects. Worth knowing which yours does.
Financial Reporting and Documentation for Bonding Purposes
The Impact of CPA-Prepared Financial Statements on Bonding Costs
For contractors, accurate financial reporting is key in the bonding process. They must offer detailed financial statements for surety bonds. These documents show their stability and promise of meeting contract terms.
Financial statements made by CPAs are highly credible. They offer a careful look at a contractor’s finances. With a CPA’s help, contractors show a clear and professional financial standing. This boosts their chance of getting better bonding terms.
The progression is worth understanding because each step costs money. Cash-basis internal statements are fine for taxes but not acceptable to underwriters, who need accrual. Above that sit CPA compilations, then CPA-reviewed statements, then audited statements. Most carriers require reviewed statements for any bond over $1,500,000.
Tom is direct about how that lands. It’s a big financial burden for something a lot of people think is just an added accounting service that has nothing to do with their ability to build roads or schools. The tradeoff is that in exchange for CPA-prepared statements, rates go down and capacity goes up. For most growing contractors, the math works.
Compiling a Comprehensive Bond Application Package
Contractors must gather all needed documents for their bond application. This package should highlight their skills, experience, and financial health.
In the bond application package, several key documents are essential:
- Completed bond application forms
- Resumes or biographies of key personnel
- Project references and details of past performance
- A detailed breakdown of current and completed projects
- Proof of licensure and insurance
- Financial statements, preferably CPA-prepared
- Work in progress schedule
- Bank reference letters
- Supplier and subcontractor references
Conclusion
We’ve looked at how much construction surety bonds cost and why they matter to contractors. For contractors, knowing these costs helps with better planning and smart money choices.
Construction bond cost comes down to three things you control, and none of them are the project. Improve your credit, your track record, and your balance sheet, and the rate follows.
The fourth thing isn’t about you at all. It’s whether the right carriers are seeing your account. A rate you can’t improve with one underwriter is sometimes just a rate that underwriter won’t offer.
If you want a real number instead of a range, or you want to know what’s actually capping your program, request a bond quote or call 303-520-0249. You’ll talk to a surety specialist, not a processor.
FAQ
How much does a construction bond cost?
Performance and payment bonds typically cost 0.5% to 3% of the bond limit. On a $1,000,000 bond package, that’s a premium between $5,000 and $30,000. Bid bonds are issued complimentary. Where you land in that range depends on your credit, your track record, and your working capital.
Who pays for a construction bond?
The contractor obtains the bond and pays the premium, but the cost is typically built into the contract price. That means it’s funded upstream by the project owner rather than absorbed out of the contractor’s margin.
How much does a bid bond cost?
Bid bonds are issued complimentary. There’s no premium. The underwriting work still happens at the bid bond stage, though, so allow 24 to 72 hours before the bid is due.
What factors affect the pricing of surety bonds?
Different things impact the price of surety bonds. Underwriters work from the three C’s: character, measured largely through personal and corporate credit; capacity, measured by your record of completing similar-sized projects; and capital, measured through working capital, cash balances, and bank lines of credit. Character carries the most weight.
How are surety bond rates calculated?
The rates for surety bonds are mostly a percentage of the bond amount. The surety company decides the exact rate. They consider the contractor’s credit, finances, and the project’s risk.
Can I get a construction bond with just my credit score?
Often, yes, on smaller limits. A FICO score above 675 can provide access to bonds up to $400,000. Excellent credit combined with references can extend that to $750,000. Larger bonds require financial statements.
How can contractors manage and lower their surety bond costs?
To reduce surety bond costs, contractors should keep a good credit score, lower debt, and boost cash flow. Moving to accrual-basis statements and adding a WIP schedule helps, as does stepping up to CPA-prepared statements as you grow. Then make sure your account is being marketed to carriers whose appetite fits your work.
How can contrWhat is the difference between performance bonds and payment bonds?actors manage and lower their surety bond costs?
Performance bonds guarantee the project completion as the contract states. Payment bonds make sure subcontractors and suppliers get paid. They are separate bonds, but carriers issue them together as one product with a single combined rate.
What are the bond requirements for public and private projects?
Public projects usually follow certain bond rules set by laws like the Miller Act. Federal contracts over $150,000 require performance and payment bonds, and state Little Miller Acts apply similar rules to state and local work. In Colorado, local public projects over $50,000 require bonds. Private projects may need bonds based on the contract and the owner’s choice.
What documentation is needed for bond approval?
For bond approval, the needed documents can change by the surety company and project. Contractors often must share financial records, insurance certificates, a filled bond application, and other financial and project-related documents. A work in progress schedule is increasingly expected on larger programs.
About Tom Patton
Tom Patton is the President of Evergreen Surety and a Certified Construction Industry Financial Professional (CCIFP), leading surety bond programs for contractors, developers, and energy producers across the United States and Canada. Drawing on 15+ years of specialty surety experience and appointments with 15+ carriers, Tom is known for building programs that perform when called upon and solving the bond problems other agents walk away from.